Where China's Composite Decking Factories Are Concentrated
China’s composite decking factories are concentrated in several eastern and southern manufacturing provinces, with Guangdong holding the largest mapped supplier cluster. Anhui, Shandong and Zhejiang also have established groups of producers, while Shanghai and Jiangsu account for smaller concentrations. These locations matter to overseas buyers because factory geography affects supplier choice, production access and the distance between manufacturing sites and export ports.
Where the main factory clusters are located
Guangdong is the largest cluster in the current directory, with 22 listed suppliers across Foshan, Guangzhou and Zhuhai. Its position reflects the province’s established manufacturing base, particularly in building materials, plastics processing and extrusion-related industries. WPC production draws on several of these capabilities. Manufacturers need equipment for mixing, compounding and profile extrusion, alongside tooling, finishing and packaging operations. A region with an existing plastics and construction-materials supply chain can support these activities without every factory having to develop its own network from scratch.

The concentration around Foshan is particularly relevant to buyers comparing building-materials suppliers. The city has a substantial manufacturing presence, while its connections to Guangzhou and the wider Pearl River Delta provide access to industrial inputs, supporting services and export logistics. Zhuhai adds another location within the same provincial cluster. For overseas buyers, Guangdong offers a relatively broad field of suppliers to compare within one province. However, geographical proximity does not establish that factories share the same production capabilities or product specifications. Factory-level checks remain necessary.
Anhui is the second-largest mapped cluster, with nine suppliers in Xuancheng, Suzhou and Guangde. Its position provides a different sourcing option from the coastal manufacturing centres. Inland industrial locations can offer access to regional manufacturing labour, processing facilities and material suppliers, while operating costs and logistics arrangements may differ from those in southern coastal provinces. The presence of several WPC suppliers suggests that the category has developed beyond isolated production sites. Buyers considering Anhui should pay particular attention to the transport leg between the factory and its chosen export gateway, rather than comparing factory quotations alone.
Shandong accounts for seven listed suppliers, located in Zibo, Linyi and Qingdao. The province has an established industrial base that includes plastics processing, manufacturing and building materials. These supporting activities are relevant to WPC production, which combines polymer processing with wood-based or other plant-fibre inputs. Qingdao also provides an important coastal logistics reference for suppliers in the province. Factories located further inland, including those around Zibo and Linyi, may have different inland transport requirements from facilities closer to the coast. The map helps distinguish these differences before a buyer begins requesting quotations.

How manufacturing geography affects sourcing
Zhejiang has six mapped suppliers across Huzhou, Jiaxing and Hangzhou. Its location within the wider Yangtze River Delta places these factories in a region with a developed manufacturing and export economy. Access to industrial suppliers, engineering services and transport infrastructure can support the production of extruded composite profiles. The cluster is also relevant for buyers comparing suppliers across neighbouring manufacturing areas rather than restricting searches to one province. Ningbo-Zhoushan Port is an important export reference for this part of the eastern coastal region, although the most suitable port depends on the factory’s actual location and shipping arrangements.
Shanghai and Jiangsu represent smaller concentrations, with three suppliers in Shanghai and two in Nanjing. Their importance is not measured by supplier count alone. Both locations sit within the wider Yangtze River Delta industrial network, where manufacturers can draw on established transport links and supporting industries. Shanghai Port provides a major export gateway, while Taicang Port is another relevant option for businesses operating around the region. Ningbo-Zhoushan Port may also enter the comparison, depending on the factory’s location, freight arrangements and destination. Buyers should assess the complete route rather than assume that the nearest port is automatically the most economical.
The distribution of suppliers reflects several overlapping manufacturing advantages, rather than a single national production centre. WPC factories require polymer inputs, wood flour or other suitable fibres, additives, extrusion machinery and downstream finishing capacity. They also need technicians who understand temperature control, profile consistency and tooling maintenance. These requirements favour locations with established plastics, furniture, construction-materials or general manufacturing industries. Local industry history can therefore help explain why suppliers appear in particular cities. It does not, however, prove that every factory in a cluster has the same technical standard or production scale.

For buyers, the practical value of a geographical directory is the ability to compare manufacturing locations before narrowing the supplier list. A search focused on Guangdong may produce a wider selection of mapped factories, while Anhui and Shandong offer alternative regional clusters. Zhejiang, Shanghai and Jiangsu are relevant when the sourcing strategy centres on the Yangtze River Delta. Port distance adds another comparison point. Shanghai Port, Ningbo-Zhoushan Port, Shenzhen Port, Qingdao Port and Guangzhou Port are among the gateways covered by the directory, alongside Tianjin Port, Xiamen Port, Taicang Port, Beibu Gulf Port, Rizhao Port, Lianyungang Port and Yingkou Port. The closest mapped port is a useful starting point, not a complete freight-cost calculation. Inland trucking, container availability, sailing schedules and the destination market all affect the final logistics decision.
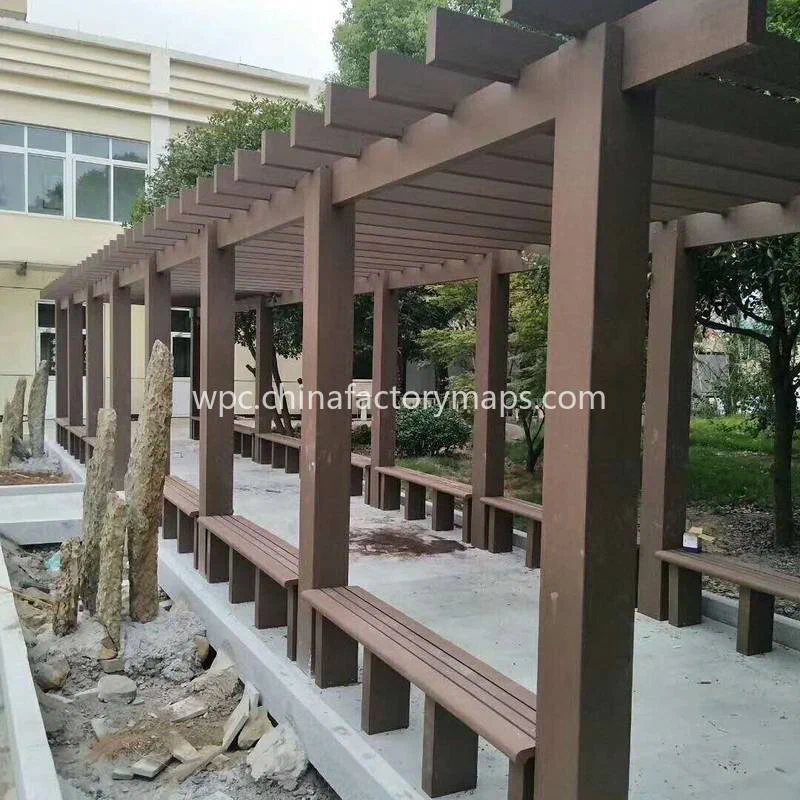
Product evaluation should remain separate from geographical selection. Composite deck pictures can help buyers compare surface textures, colours, board profiles and visible finishing details, but photographs cannot establish formulation or structural performance. Technical checks should cover the polymer and fibre composition, extrusion consistency, dimensional tolerances, intended application and available test documentation. WPC expands and contracts with temperature, so installation systems require appropriate board gaps and a ventilated substructure. The material generally resists moisture and insect damage better than untreated timber, but it is not indestructible or absolutely waterproof. Sustained ultraviolet exposure can also cause colour fading. Buyers should request product samples and installation specifications alongside factory information, particularly when sourcing for projects with demanding outdoor exposure.
FAQ
Q: Which Chinese province has the largest mapped concentration of WPC factories?
A: Guangdong has the largest concentration in the current directory, with 22 listed suppliers across Foshan, Guangzhou and Zhuhai.
Q: Which export ports should buyers compare when sourcing composite decking from China?
A: Shanghai Port, Ningbo-Zhoushan Port, Shenzhen Port, Qingdao Port and Guangzhou Port are important comparison points. The appropriate gateway depends on the factory’s location, inland transport arrangements and the destination shipping route.
Featured Suppliers
Verified premium suppliers on our map.